What Is Mortgage Insurance Premium and How Is It Calculated?
Last Updated on October 10, 2026 by chada sravas
How Mortgage Insurance Premium Is Calculated
In order to determine the mortgage premium, one needs to consider the loan amount, the relevant insurance rate, and the regulations of the mortgage program. Mortgage insurance is calculated in different ways depending on whether a conventional mortgage uses Private Mortgage Insurance (PMI) or a Federal Housing Administration loan uses Mortgage Insurance Premiums (MIP).
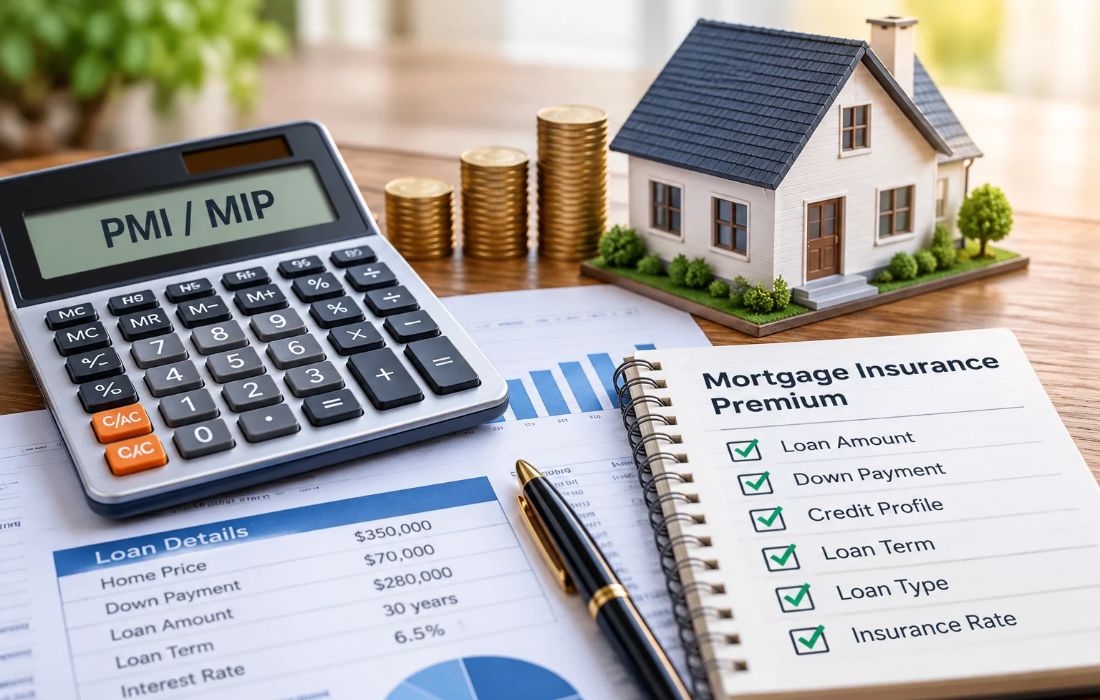
To assess the risk of many standard loans, the insurer observes elements like the down payment, loan-to-value (LTV) ratio, credit profile, mortgage type, and loan duration. As for FHA premiums, they are based on the established FHA premium rate schedule, including the base loan value, loan-to-value (LTV) ratio, and duration of the loan.
A larger down payment generally reduces the amount borrowed and the LTV ratio. This can affect whether insurance is required and how much it costs. However, a smaller loan does not automatically guarantee a lower premium rate, because other underwriting and program rules also apply.
Factors That Affect Mortgage Insurance Premiums
Loan-to-value ratio (LTV): The LTV ratio compares how much money is borrowed compared to the given value of the property. For instance, if a home is valued at $300,000, but the mortgage is $270,000, the LTV will be 90%. Essentially, the higher the LTV, the greater the lender’s risks and the requirements and costs of mortgage insurance.
Down payment: The amount of money that you will need to borrow is based on the down payment. A down payment of 20% on a qualifying conventional mortgage typically exempts you from paying for PMI. The insurance specifications for FHA loans differ.
Credit profile: In traditional PMI, credit history and things related to credit can affect the premium that the insurer offers. Borrowers with different credit profiles might receive different quotes for similar loans.
Loan amount and term: The amount borrowed and the repayment period can affect the premium calculation. FHA uses specific rate categories based on the loan characteristics and applicable rules.
Mortgage program: Conventional PMI and FHA MIP use different pricing structures. Comparing their premiums requires examining the complete loan terms, not just the insurance rate.
How to Calculate a Mortgage Insurance Premium
For a simple estimate, an annual premium can be calculated by multiplying the applicable annual premium rate by the balance used for the calculation.
Illustrative formula:
Annual premium = Applicable balance × Annual premium rate
Monthly premium = Annual premium ÷ 12
For example, suppose a borrower has a $250,000 mortgage and an illustrative annual insurance rate of 0.50%.
Annual premium = $250,000 × 0.005 = $1,250
Estimated monthly premium = $1,250 ÷ 12 = $104.17
In this simplified example, the estimated premium is approximately $104.17 per month.
This is an illustration, not a quotation for a real mortgage. Standard PMI pricing is different for each insurer and depends on the characteristics of the loan. FHA yearly MIP calculations can be based on the average remaining balance due according to the amortization schedule of the loan, which is why it may differ from the figure calculated from the original loan amount.
How FHA Upfront Mortgage Insurance Premium Is Calculated
Now, if you want to secure an FHA forward mortgage, be prepared to shell out an upfront mortgage insurance premium (UFMIP), since nearly all of them require payment of the UFMIP before processing your loan application.
The Department of Housing and Urban Development (HUD) has fixed the basic UFMIP for FHA purchase and refinance loans at 1.75% of the loan amount.
The calculation is:
Upfront MIP = Base loan amount × Applicable upfront rate
For example, if the base FHA loan amount is $250,000:
Upfront MIP = $250,000 × 1.75% = $4,375
The upfront premium in this example is $4,375. Depending on the loan arrangements, it may be paid at closing or financed into the mortgage. If financed, it increases the loan balance and the amount the borrower repays.
The upfront premium is separate from the annual MIP. The annual rate depends on the applicable FHA schedule, including the loan term, base loan amount, and LTV ratio. Therefore, the upfront calculation alone does not represent the total mortgage insurance cost.
Also Read : What Does Mortgage Insurance Cover?
Upfront Premium vs. Monthly Mortgage Insurance Premium
The initial premium is paid by the borrower at loan origination, and the monthly premium must be paid by the borrower through regular payments. Some mortgage offerings will use one of these payment options; others may use both.
The upfront MIP for FHA loans is usually computed as a percentage of the principal loan amount. The Annual MIP is calculated using the respective annual rate and the balance calculation approach required by HUD.
The payment option for conventional PMI is determined by both the policy and lender. Borrowers could be faced with monthly premiums that are paid by the borrower, a one-time premium that is paid upfront, or lender-paid insurance, which will be reflected in the mortgage interest rate.
Check that the insurance cost being quoted is either an upfront or blanket payment when comparing loan offers. A loan with a lower monthly payment can have a higher upfront fee or interest rate.
How to Estimate the Total Mortgage Insurance Cost
The first step to determine the right amount is to identify the mortgage program in question and the corresponding premium rate. Then, you should find out the way the premium is calculated, how long it will be in effect, and whether the upfront cost requires financing.
For standard PMI, ask for a premium price quote by submitting a request based on the amount of the loan, the amount of the down payment, and the credit profile. For FHA loans, obtain the current HUD premium schedule or the lender’s FHA calculation.
Make sure to check the Loan Estimate to determine the mortgage insurance expenses and other costs associated with the loan. The offers must be compared using the same assumptions with regard to the price of the purchase, down payment, loan duration, and mortgage rates. This will allow you to compare the total cost of borrowing rather than simply the monthly costs of insurance.
